Life coaching is unregulated in all 50 states, which removes the licensing board but not the lawsuit. A client who disputes an outcome or claims your guidance caused harm can file a civil claim with nothing standing between them and your personal assets. This breakdown covers the real rates and what moves them, plus the coverage limits corporate clients require before they'll hire you.
How much does life coach insurance cost?
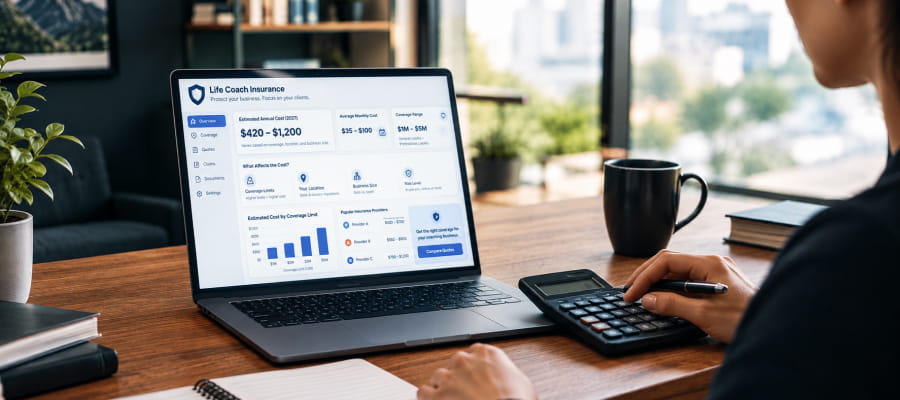
Most solo life coaches pay between $10 and $60 per month, the life coach insurance cost average most quotes settle into whether billed monthly or annually. Rates start near $10.34 monthly for coaches with $50,000 or less in gross annual coaching income and rise to about $37.83 monthly for businesses above $250,000 in annual sales, with professional and general liability combined averaging around $59 monthly across the market.
The cost of professional liability insurance for life coaches lands in a similar band annually. Standalone professional liability runs roughly $464 per year through established carriers, while a full Business Owner's Policy reaches about $686. Coaches paying more than $700 a year without employees or premises are usually over-insured for their actual exposure.
What Drives Life Coach Insurance Premiums
Insurers weigh four things when they price a policy. Income matters most: gross coaching revenue sets your limit requirement, which is the largest single lever, since coverage scales to the money at risk. Location matters next, and delivery model and niche adjust the price from there. A fifth factor, claims history, matters just as much at renewal: insurers reprice coaches who have filed a prior claim higher regardless of how that claim was resolved, while a clean history keeps renewals close to the entry rate.
Geography is one of the biggest swings in the average cost of insurance for life coaches, and it matters more than most coaches expect. Coaches in New York and Washington, D.C. average around $37 monthly for professional liability, against roughly $28 in Maine, North Carolina, and North Dakota, a 32% gap driven by how often professional claims reach court in each state.
A virtual-only practice also prices below one renting office space, since general liability exposure drops without a physical location. Coaches structuring their business around those choices can work through the wider cost picture in this online coaching pricing guide.
What Life Coach Liability Insurance Covers
Liability insurance for life coaches breaks into two core policies, usually sold together, defined in more detail in the NAIC's small business insurance guide:
- Professional liability (errors and omissions)
Claims about the quality, outcome, or consequences of your coaching, including a client alleging your guidance caused financial loss or emotional harm. This is the policy your practice runs on.
- General liability
Physical events are the core of it: a client injured at your office, or property you damage during a session. It also includes personal and advertising injury claims that cover reputational harm from your content.
Three add-ons matter depending on how you work:
- Optional Add-Ons Worth Checking
- Cyber liability protects client records for online-only practices.
- Sexual abuse and molestation coverage funds defense against false allegations.
- Workers' compensation becomes a legal requirement the moment you hire anyone.
Why Life Coaches Need Insurance Despite No Licensing Requirement
Do life coaches need insurance even though no state licenses the profession? Yes, and the lack of regulation increases the risk rather than lowering it. An ICF credential is a professional designation, not a mandatory-insurance requirement, and that gap leads coaches to assume coverage is optional. A single claim you win outright can exceed a decade of premiums in defense fees alone. The SBA lists liability coverage as a baseline safeguard for any solo service business, not an optional extra, in its own guide to getting business insurance.
Insurance is only half the protection. Coaches operating as a sole proprietor carry that risk personally even with a policy in place, since a judgment above your coverage limit can still reach personal assets; forming an LLC before you take on paying clients closes that gap and is typically the cheaper of the two safeguards to put in place first.
Corporate clients settle the question in practice. Most require a certificate of insurance at $1 million per occurrence and $2 million aggregate before signing, and some enterprise legal departments demand $2 million per occurrence plus umbrella coverage. Coaches without a policy simply lose those contracts.
The same documentation discipline that satisfies a corporate client also improves intake, which this comparison of client onboarding software covers for coaching businesses.
What Happens If You're Sued Without Insurance?
You cover every dollar of your own legal defense, even if you're never found liable. Without a policy, a contested claim's attorney fees come directly out of personal savings. If your practice isn't formed as an LLC, a judgment can reach beyond the business into your personal assets too. A policy also puts a law firm on the case within days of a claim, which is often the difference between a dispute that closes quietly and one that drags on for years and costs more than the policy ever would.
Where Life Coaches Buy Insurance
Insurance for life coaches usually comes as a bundle: professional and general liability, quoted and issued the same day, through carriers built for solo service businesses. Hiscox, Next Insurance, Thimble, CoverWallet, and Insurance Canopy all sell direct to coaches online. The International Coaching Federation also runs a partner directory offering members discounted rates through vetted providers, which is worth checking before buying elsewhere, especially if you want a carrier familiar with coaching rather than consulting broadly.
Coverage isn't identical across carriers, and some exclude specific coaching modalities from an otherwise standard policy. Confirm your modality and any add-on services are explicitly listed before buying, and recheck at renewal if you've added a new one. Coaches who pick up an excluded modality typically layer a second policy on top rather than switching carriers, since replacing a policy already priced in your favor usually costs more than adding coverage for the gap alone.
Recommended Coverage Limits for Life Coaches
Coverage limits scale in three steps as your practice grows, and each step changes your life coach insurance cost:
- Baseline: $1 million per occurrence and $2 million aggregate. This is the market standard for both professional and general liability, and it clears the requirement most corporate and venue contracts specify.
- Growth tier: a $3 million aggregate limit, running about $33.58 per month or $378 per year, for coaches running group programs or working with corporate clients.
- Added protection: the life coach professional liability insurance cost per year rises by just $300 to $600 for each extra $1 million layer, the cheapest protection available once revenue passes six figures.
Premium Differences by Coaching Niche
Niche is one of the biggest swings in life coach insurance cost. Health, financial, and mental wellness coaching carry the highest rates, since those niches touch areas where a client can claim tangible, measurable harm, which raises both claim frequency and settlement size. Some insurers exclude specific niches or group programs entirely, so read the exclusions before assuming a quote applies to your practice.
Career and executive coaching sit in the middle, while general life coaching prices lowest. Coaches who have expanded their services across niches should reconfirm coverage at renewal, since a policy bought for general coaching may not respond to a claim from newer work. Running that check alongside a broader coaching business review keeps the policy matched to the practice you actually have.
Final Thoughts
Get quotes at $1 million per occurrence and $2 million aggregate. Confirm your niche isn't excluded before you buy, and get professional and general liability together rather than as separate policies. Most coaches over-research this decision and under-buy the coverage, when the difference between the cheapest and the right policy is usually under $30 a month.
Life coaching insurance pricing changes annually and varies by state, so treat every figure here as a benchmark to quote against, not a rate you will be offered.
Client disputes usually start with unclear expectations. Documented intake, signed agreements, and session records prevent more claims than any policy settles. Book a demo to see coaching agreements, intake forms, and session notes running inside one branded client app.